First Atlantic Bank Grows Lending 67% as Customer Deposits Hit GH¢19bn
First Atlantic Bank PLC expanded its lending by 67% in the first nine months of 2026, supported by a 37% increase in customer deposits, as the Bank strengthened its balance sheet and diversified its revenue streams.
The growth in lending to GH¢2.5 billion, against customer deposits of GH¢19 billion, points to significant room for the Bank to deepen its support for businesses and households while maintaining a strong deposit base.
Chief Executive Officer, Odun Odunfa, said the performance reflected growing customer confidence and the resilience of the Bank’s business model.
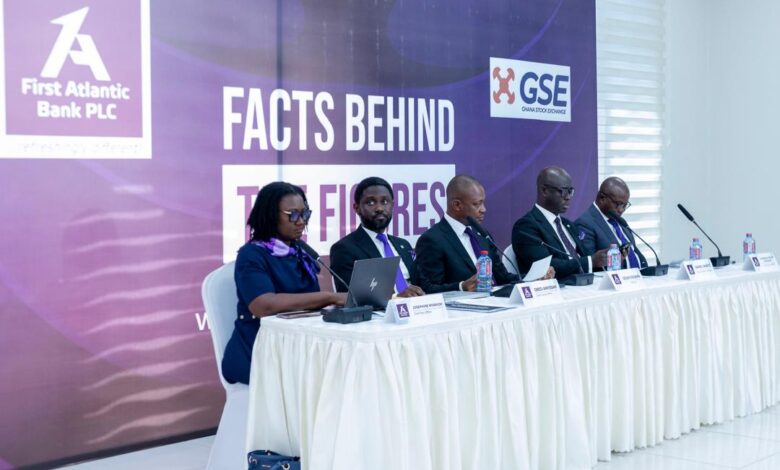
Speaking at the Facts Behind the Figures forum organised by the Ghana Stock Exchange (GSE), he said deposit mobilisation had strengthened the Bank’s ability to extend credit while making banking services more accessible and convenient.
“Our performance in the first nine months of 2026 reflects the resilience of our business. Strong customer confidence has supported deposit growth, enabling us to extend credit to more businesses and households while making everyday transactions more accessible and convenient,” he said.
Total assets rose by 39% year-on-year to GH¢21.8 billion at the end of September, while shareholders’ funds increased by 33% to GH¢2.4 billion.
Investment securities also grew by 44% to GH¢5.2 billion, reflecting an expansion in the Bank’s asset base.
On profitability, net interest income increased by 37% to GH¢524 million, helped by a 33% reduction in interest expenses as funding costs eased.
Net fee and commission income recorded a stronger 55% growth to GH¢200 million, pointing to increased transaction volumes and greater customer activity.
These gains lifted operating income by 31% to GH¢821.7 million, exceeding the 23% growth in operating expenses.
Profit before tax consequently increased by 4% to GH¢386 million, while profit after tax rose by 3% to GH¢261 million compared with the same period in 2025.
The improvement in income relative to expenses also helped reduce the Bank’s cost-to-income ratio to 53.5% from 56.7% a year earlier, despite continued spending on personnel, technology and operational infrastructure.
Mr Odunfa said the Bank was maintaining cost discipline while investing in the capabilities required to support its expansion.
He also disclosed that the Bank’s entry into Liberia was progressing, describing the expansion as an important step towards building a stronger regional presence.
Management’s next priority, he said, would be to convert the growing customer base into deeper and more sustainable banking relationships, while increasing fee income and ensuring that operating expenses grow more slowly than revenue.
The Bank also intends to strengthen its competitive position in Liberia and continue investing in digital platforms and new products.
With its current deposit base providing substantial funding capacity, management said it could expand lending to businesses and individuals while complying with the Bank of Ghana’s new directive on non-performing loans.
Mr Odunfa said prudent risk management would remain central to the Bank’s strategy as it pursues growth and long-term value for stakeholders.